
HN
@heloix_news
Growth
Gaming Commerce Unlocked: How PlaySuper Is Converting In-Game Victories into Real-World Rewards
#PlaySuper#gamingcommerce#gamingrewards
Kommentieren
2.2K
Rodrica Michael
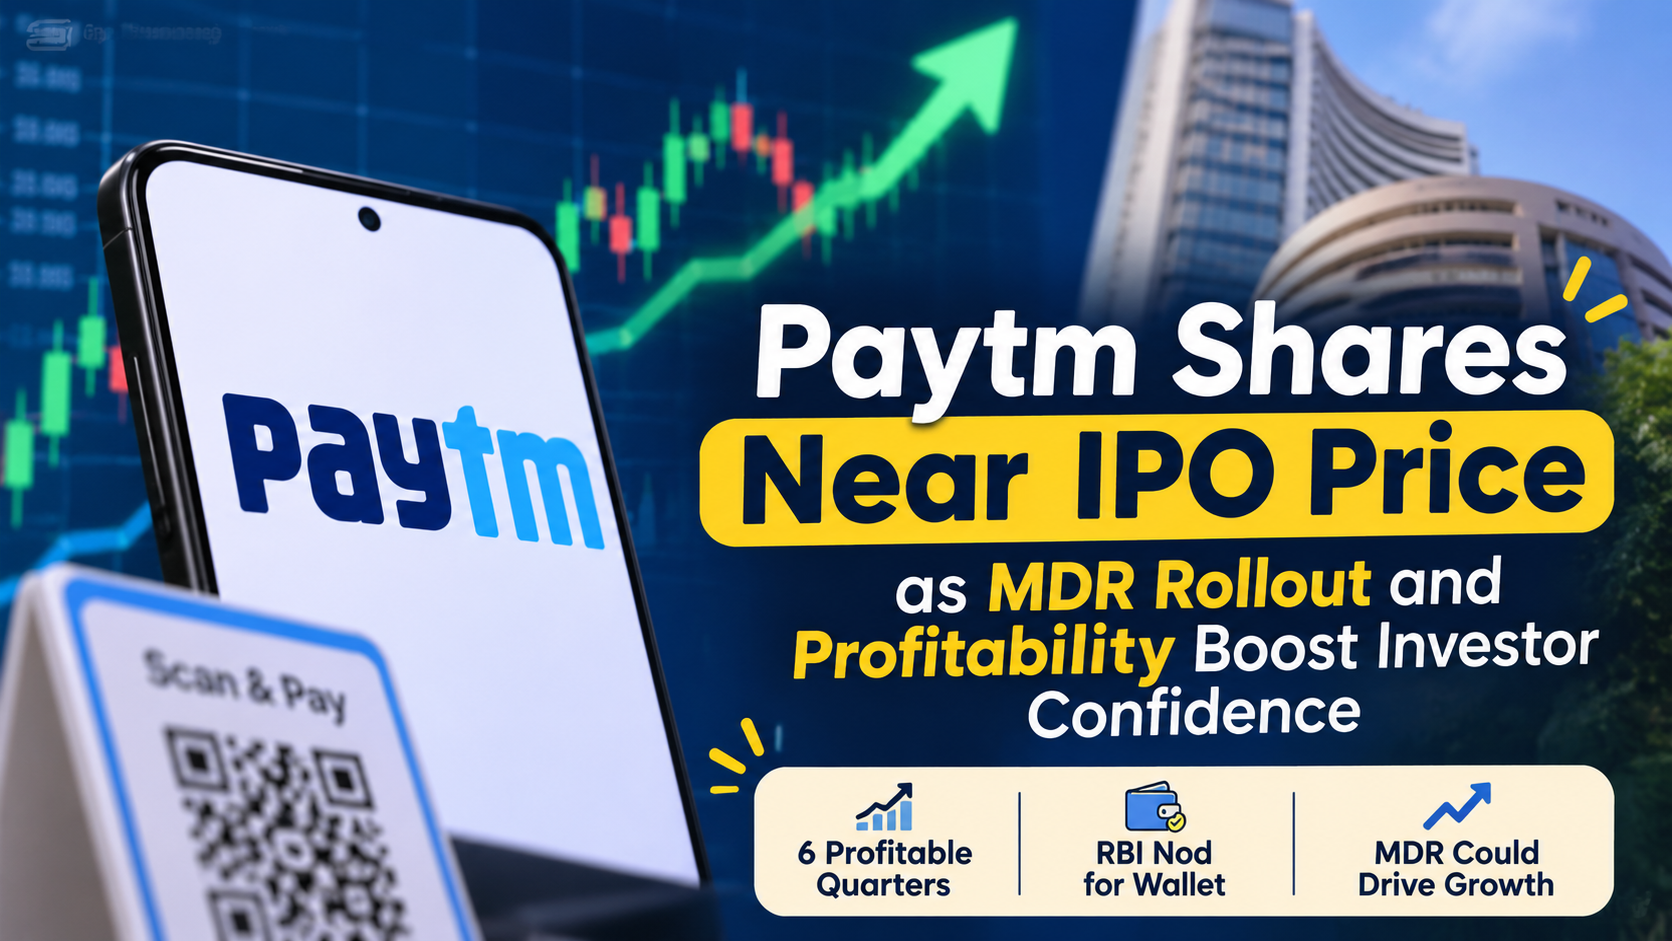
Shares of One 97 Communications, the parent company of Paytm, are gradually moving closer to their IPO price of Rs 2,150, supported by improving financial performance and positive regulatory developments.
The stock was trading at Rs 1,939.70 on Friday, November 13, around 9.8% below its IPO price. During the trading session, shares touched a fresh 52-week high of Rs 1,960.
Paytm shares have gained nearly 7.7% over the past two trading sessions and have more than doubled from their 52-week low of Rs 930.60 recorded in March 2026.
The company's recovery comes amid improving profitability, regulatory progress and expectations of additional revenue from the proposed merchant discount rate (MDR) on eligible UPI transactions.
## Six Consecutive Profitable Quarters
Paytm has reported profits for six consecutive quarters, supported by revenue growth, better operating efficiency and improved cost management.
In the second quarter of FY27, the company reported operating revenue of Rs 2,648 crore, representing a 28.5% increase year-on-year. Its net profit increased more than tenfold to Rs 225 crore.
For the first half of FY27, Paytm recorded operating revenue of Rs 5,096 crore and a net profit of Rs 491 crore.
The consistent improvement in financial performance has helped strengthen investor confidence in the company.
## RBI Approval Brings Hope for Wallet Business
Another positive development came on November 13, when the Reserve Bank of India (RBI) granted in-principle authorisation to Paytm Payments Services Limited (PPSL), a wholly owned subsidiary of One 97 Communications, to issue and operate prepaid payment instruments (PPIs), including digital wallets.
The approval is an important step towards reviving Paytm's wallet business, which was previously operated through Paytm Payments Bank.
However, PPSL will need to complete the required system and cybersecurity audits and obtain final RBI authorisation before resuming wallet issuance.
## MDR Rollout Could Create a New Revenue Stream
The proposed implementation of a 40 basis point merchant discount rate (MDR) on eligible UPI merchant transactions could provide another growth opportunity for Paytm.
The move is expected to create an additional revenue stream and improve the monetisation of its payments business.
Bank of America, in its October report, maintained a Buy rating on Paytm, highlighting the potential benefits of MDR implementation.
Bernstein has also expressed confidence in the company's prospects. In August, the brokerage raised its target price on Paytm from Rs 1,500 to Rs 2,200 while retaining its Outperform rating.
With improving financial results, progress in its wallet business and the expected MDR rollout, Paytm is gradually rebuilding investor confidence and moving closer to its IPO price.
Bitte um einen Kommentar zu verfassen
Noch keine Kommentare
Teilen Sie als erste Person Ihre Gedanken.
@heloix_news
Growth
@heloix_news
Growth
@heloix_news
Growth
Abonnieren Sie die neuesten Einblicke zu Technologie, Unternehmenswachstum und digitaler Transformation.